The next morning, Miriam arranged a meeting with Patricia Lowe, the retired clerk who had previously confirmed that Schedule B was kept separately under Leonard Voss’s instructions. Patricia had agreed to provide a supplemental statement after learning that the investigators had traced the nominee account to Northfield Holdings. She wanted to explain why she had remained silent about the private schedule for so many years.
We met her in a quiet office near the records archive. She arrived carrying a brown folder secured with a length of string. Her hands trembled slightly as she placed it on the table, but her voice was steady when she began.
“I told you I kept the schedule separately,” she said. “I did not tell you that I made a copy before I handed it over.”
Rebecca leaned forward. “You kept a copy of Schedule B?”
“Not the entire schedule. Only the pages that were marked for correction. I made them because the figures did not balance, and I thought someone would eventually ask me to explain the changes.”
Patricia had worked in the accounts department during the final months of 1987. She remembered the pressure to close the settlement before the end of the year, the repeated telephone calls from Voss’s office, and the insistence that the reserve could not remain frozen without jeopardizing the company’s financing. The official explanation had been that the outstanding claims were administrative problems that could be reconciled after the money was released.
Arthur had disagreed. Patricia remembered him arriving with a list of unresolved payments and asking her to show him the original claimant schedule. He had pointed out that three entries had been marked settled even though the authorization files were incomplete.
“He was not trying to stop every payment,” she said. “He was trying to stop the final release from being treated as proof that every claim had been resolved.”
That distinction mattered. The documents had sometimes portrayed Arthur as an obstructionist who refused to approve a settlement that everyone else considered practical. Patricia’s memory suggested that he had wanted the legitimate payments made but insisted that the company preserve the distinction between verified claims and unresolved ones.
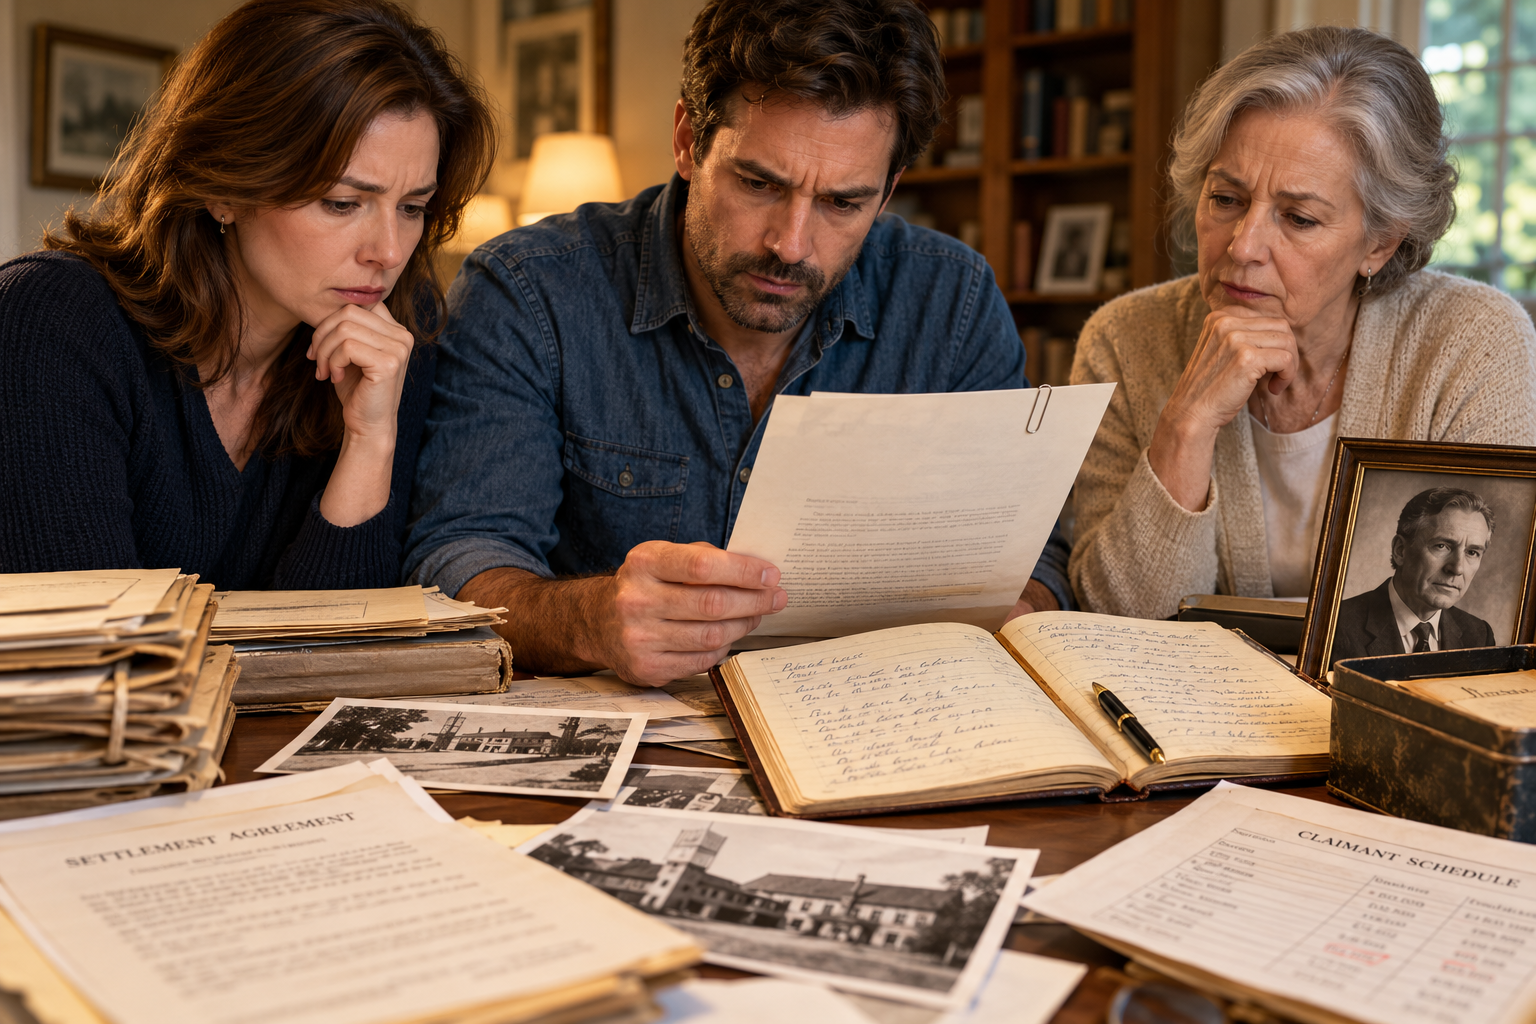
She untied the folder and removed three photocopied pages. They were faded, but the columns remained legible. The first listed the original claim amounts. The second recorded proposed payments. The third showed the status of each claim and the person responsible for confirming that payment had been received.
Clara Whitcomb’s entry was marked authorization pending. The Miller family’s entry showed a partial payment, with the balance unresolved. Bell Equipment’s line had a handwritten note stating that the supporting receipt had not been located. None of the three entries was marked fully settled on Patricia’s copy.
Yet the later version of Schedule B, which we had already examined, described all three as resolved.
“Who changed it?” Rebecca asked.
Patricia took a breath. “I saw Voss’s assistant carrying the corrected pages. I did not see the assistant make the changes. I saw Voss take the folder into his office, and when it came back, the status column had been altered.”
“Did you tell Arthur?” I asked.
“I tried. He was already asking questions about the release. I left a message through the records office, but I don’t know whether he received it. That was the last time I saw him in the building.”
Patricia could not prove that Voss personally changed the entries. She had not witnessed him writing on the pages, and the assistant might have acted under instructions from someone else. But she remembered that Voss had asked her to keep the corrected schedule separate from the main accounting file until the release was processed.
The photocopies were not a complete answer, but they established something important: before the final release, at least one employee had preserved a version of the claimant schedule that did not support the later declaration that every claim was settled.
Miriam examined the pages carefully. The copy bore a faint date stamp and a filing reference that matched the old accounts register. She asked Patricia how she had kept it safe.
“I took it home in my handbag,” Patricia said. “I told myself I was protecting the company’s records. I did not understand how far things had gone, and I was afraid that if I challenged a senior lawyer without proof, I would lose my job and the papers would disappear anyway.”
“Why did you not come forward when Arthur died?” Rebecca asked.
Patricia looked down at her hands. “Because I believed the dispute had ended. Then I heard that Arthur’s family was being blamed for delays in the settlement. I knew that was not the whole truth, but I had no idea where his papers had gone or whether anyone would listen to me.”
She paused before adding that she had also been afraid of being accused of stealing company records. The pages were copies, but she had no formal permission to take them home. She had spent years convincing herself that keeping them had been enough.
Miriam assured her that the investigators would decide how to handle the provenance of the documents. What mattered now was that Patricia had preserved them and was willing to explain how she obtained them. She agreed to provide a signed statement and allow the copies to be compared with the original register.
Before the meeting ended, Patricia produced one more item from the folder. It was a small handwritten note on the back of a routine filing slip. The note had no signature, but Patricia recognized the handwriting as belonging to a records supervisor who had worked under Voss’s direction.
The note read: Release must precede reconciliation. Investor will not wait beyond Friday.
Below it was another line: Do not send corrected schedule to Arthur until approval is entered.
Rebecca looked up. “That means they knew the schedule was not ready.”
“It means someone knew it was not ready,” Miriam replied. “We still need to identify the writer and determine who gave the instruction.”
Patricia said the note had been found clipped to a file that was supposed to contain the final release. She had copied it because the wording troubled her. The date on the filing slip placed it two days before the transfer to Northfield Services.
Miriam asked whether Patricia remembered any discussion of the investor who had threatened to withdraw support. Patricia recalled hearing that a large investor was impatient with the unresolved claims and wanted the reserve distributed before the company’s year-end accounts were prepared. She had never met the investor and could not say whether the threat was genuine or merely used to pressure the staff.
“But Voss kept saying the investor had already been promised a date,” she added. “He said the company could not afford to miss it.”
The note made the urgency more concrete. The release was not delayed because every claim had been verified. It was pushed through because someone wanted the money moved before reconciliation was complete.
After the meeting, Miriam took the copies to the investigators. Rebecca and I stayed behind with Patricia, who seemed relieved to have finally told someone what she remembered. She asked whether Arthur had left a notebook.
“Yes,” I said. “Several entries suggest he knew the third transfer was unauthorized.”
Patricia closed her eyes briefly. “Then he knew more than I did.”
She told us that Arthur had once asked her whether a private schedule could be amended after the release had been signed. She had answered that changes could be made to correct clerical errors, but any change that altered a claimant’s status needed supporting documentation. Arthur had replied that he was afraid someone would use a clerical correction to turn an unresolved claim into a completed one.
“He said the difference was not in the number,” Patricia recalled. “It was in the authority behind it.”
On our way home, Rebecca compared Patricia’s copy with the version recovered from Ruth Danner’s estate. The claimant amounts matched, but the status markings did not. The corrected schedule had converted pending or partial entries into settled claims without adding the missing receipts or authorizations.
That gave the investigators a way to test the records. If the final settlement had genuinely been completed, there should have been payment confirmations supporting those changes. If the confirmations were absent, the altered schedule could not independently prove that the claims had been paid.
Later that evening, Miriam called. The investigators had located an additional accounting entry showing that the transfer to Northfield Holdings had been posted before the claimant reconciliation was complete. The entry was not in the official distribution summary. It appeared in a secondary ledger used to track advances and repayments.
The same ledger recorded a charge against the settlement reserve for legal services, but the amount did not match Voss’s invoice. A portion of the difference had been transferred to the partnership that owned Northfield Holdings.
Miriam emphasized that this did not yet prove Voss personally received the money. The partnership records and account movements would need to be authenticated. But the combination of the altered claimant schedule, the premature release, and the undisclosed transfer made the settlement increasingly difficult to explain as a routine administrative error.
Before hanging up, she told us the investigators had identified a former employee who might know who controlled the partnership. He had been a junior accountant in the office at the time and had since moved away. His name was Daniel Mercer.
I recognized it immediately.
Daniel Mercer was the man Harold Finch had mentioned only once, almost in passing, when he recalled that a junior accountant had questioned the repayment entry shortly before leaving the company. According to Finch, the accountant had warned that the same funds were being described differently in separate ledgers.
For nearly forty years, his objection had survived only as a brief recollection.
Now the investigators had found his name on a payroll record, beside a departure date that fell just three weeks after the disputed transfer.
Click here to continue reading: PART 24: The Accountant Who Left Before the Books Closed Finally Explains What He Saw in the Final Weeks of 1987
My Mother Wrote Six Ordinary Numbers, but the Man Behind the Counter Suddenly Forgot How to Breathe
Part 23 of 30