The investigators opened the envelope under controlled conditions and documented every mark on its exterior before removing the contents. The signature page was still inside, folded once and held in place by a narrow paper band. It bore the same reference number as the private financing agreement and a date matching the week before the disputed transfer.
The page contained three signatures. One belonged to Leonard Voss, signing as legal coordinator. Another was Robert Vale’s, listed beside a corporate execution clause. The third signature had been written in full rather than represented by initials, and it belonged to a person whose name we had seen in none of the official claimant records.
Miriam did not tell us the name over the telephone. She said the investigators needed to verify the signature against other documents and establish whether the person had signed in a personal or corporate capacity. She would not allow us to draw conclusions from a page that had only just been recovered.
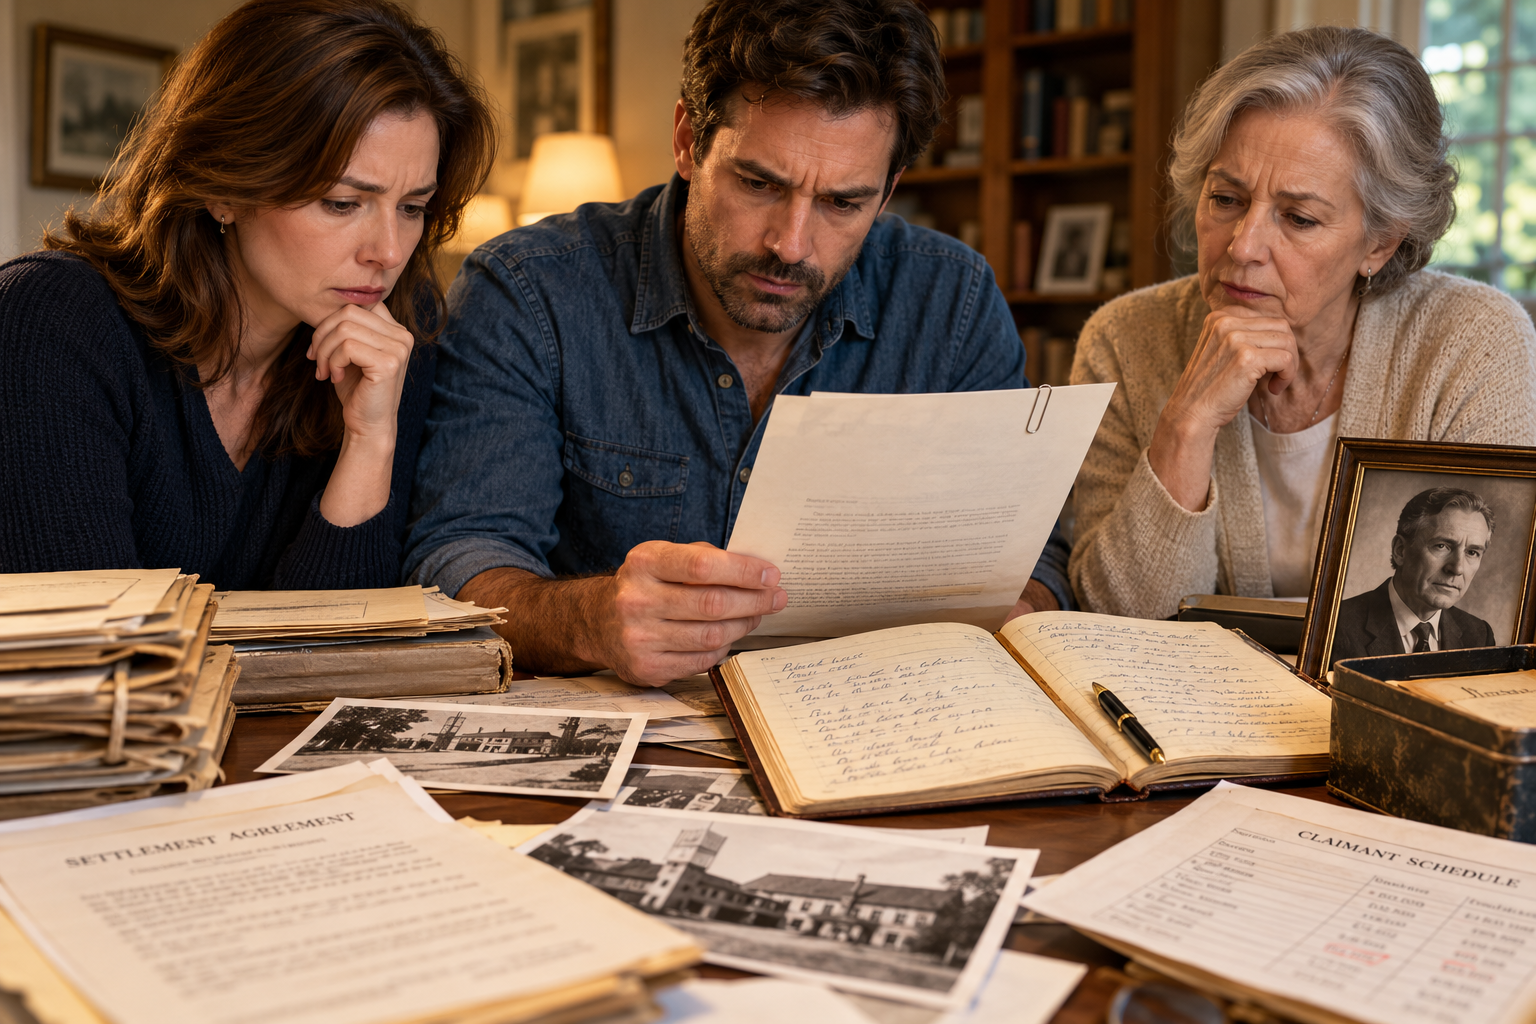
That evening, Rebecca and I sat at the kitchen table with the copies we were allowed to review. We went through the dates again, tracing the sequence from Arthur’s objection to the final release. The private agreement had been prepared before the reserve was transferred. The claimant schedule had been altered shortly before the release. The nominee account had received the third payment and forwarded it to Northfield Holdings. The money had then been used to repay an advance that depended on the register being marked complete.
Every document seemed to answer one question while opening another. We knew the arrangement had been planned in advance, but we still did not know whether the principal had understood that the three claimants remained unpaid. We knew Voss and Vale had participated, but we could not yet establish what each man had been told. And we knew Arthur had objected, but the records still did not explain how his alleged approval had been inserted into the release.
Miriam called the next morning. The signature had been compared with records held by the relevant corporate registry, and the examiner found sufficient similarities to justify further investigation. The signature belonged to Edmund R. North, a private investor who had provided financing to Northfield Holdings and whose name appeared in several old corporate filings.
North was not listed as a claimant, a company director, or a recipient in the official settlement summary. Yet the private agreement identified him as the principal beneficiary of the advance. The agreement stated that the reserve transfer would satisfy the outstanding obligation once the settlement register showed completion.
“So the money was his,” Rebecca said.
“Some of it may have been used to repay an advance he was owed,” Miriam replied. “We still need to determine the legal basis of that advance and whether the repayment was authorized. The agreement does not establish that every dollar transferred was his property or that the settlement reserve could lawfully be used to pay him.”
The distinction was important. North could have been a legitimate creditor whose repayment was improperly handled, or he could have been a beneficiary of an arrangement designed to conceal the diversion of funds. The documents did not yet prove which explanation was correct.
The investigators located a surviving corporate file for North’s investment partnership. It showed that he had supplied financing to the company years earlier, but the original loan agreement was incomplete. The amount recorded as outstanding before the settlement did not match the sum repaid through the nominee account. The difference could have reflected interest or fees, but the private agreement contained no calculation explaining the excess.
Miriam said the investigators were trying to establish whether the advance had been secured against the reserve before the disputed claimants’ rights arose. If the reserve had been committed to repayment without proper authorization, the transfer might have violated the settlement terms even if North had been owed money.
The signature page also contained a clause that had not appeared in the partial agreement recovered earlier. It stated that the principal beneficiary would not be required to provide proof of the underlying advance to the company’s ordinary directors, provided that the legal office certified the repayment as part of the final settlement.
Rebecca read the clause twice. “That is why the agreement was kept out of the ordinary register.”
“It may explain why the parties wanted it kept separate,” Miriam said. “But we still need to know who drafted the clause and whether the directors were told about it.”
The clause placed Voss at the center of the legal certification and Vale at the center of the corporate execution. North was the beneficiary, but the agreement did not say that he had ordered anyone to alter the claimant schedule. It said only that he would receive repayment once the register showed completion.
That was where Arthur’s role became more troubling. The private agreement included a note beside the completion clause: If A.B. declines approval, legal certification will be used to proceed.
The note was handwritten. Its author had not been identified. It suggested that the people arranging the transaction had anticipated Arthur’s refusal and had prepared an alternative way to complete the transfer.
Miriam warned us that the note could have been added after the agreement was signed. It might be a later annotation, an internal reminder, or evidence that the parties planned to bypass Arthur. A handwriting comparison and examination of the ink could help establish when it was written, but even then, the context would matter.
I could not stop thinking about the phrase if A.B. declines approval. Arthur had not been a minor participant whose objection could be dismissed as a clerical inconvenience. His approval was the thing the second release was supposed to establish. If the agreement anticipated proceeding without him, then the signature attributed to him might have been intended to conceal the fact that he had refused.
The investigators questioned Vale again after showing him the complete signature page. He acknowledged that he had signed the agreement as a corporate representative, but he said he had not drafted it and had relied on Voss to confirm its legality. He admitted knowing that North was the principal beneficiary of the advance, although he maintained that he believed the repayment would be reconciled after the final release.
When asked about the clause referring to Arthur’s refusal, Vale said he did not remember seeing it. He also denied knowing that Arthur had submitted a written objection before the transfer. The investigators had the legal archive entry showing that the objection had been received and routed to the private file, but they had not yet established whether Vale had personally seen it.
Voss’s response was more guarded. Through his representative, he stated that the agreement was a private financing document and that its terms should not be interpreted as evidence of wrongdoing. He said the company had been entitled to repay a valid advance and that the settlement’s final release was prepared according to the information available at the time.
He did not explain why the claimant schedule had been changed before the supporting receipts were found. He did not explain why Arthur’s approval was recorded when Vale admitted he had never seen Arthur sign the document. And he did not explain why the private agreement anticipated that the transfer could proceed even if Arthur declined approval.
Miriam told us that the investigators would need to give Voss an opportunity to answer those questions formally. A refusal to provide a complete explanation was not proof of guilt, and legal representatives often advised clients not to comment on documents until they had reviewed them. But his response had not resolved the central contradictions.
Meanwhile, the bank records offered a new detail. The nominee account had received the third transfer, then sent the larger portion to Northfield Holdings. The remaining amount was divided between administrative expenses and a smaller payment to an account connected to the partnership that had managed the advance. The figures corresponded closely to the amounts in the private agreement, except for a final adjustment that had not been explained.
The adjustment was labeled reconciliation reserve. It had been held in a separate account and was not included in the claimant ledger. Investigators had traced it through one additional transfer, but the destination record was incomplete. The account had been closed, and the surviving bank index identified only a reference number and the name of a trust administrator.
The trust administrator’s records showed that the account had been opened to hold funds pending a determination of ownership. That seemed inconsistent with the claim that the settlement had been fully completed. If all obligations had been resolved, there would have been no reason to keep a separate reserve for an undetermined beneficiary.
The trust record also listed a condition for releasing the funds: confirmation from the person responsible for reconciling the claimant schedule. The named person was Arthur Brooks.
“He was supposed to verify the claims before the money could be released,” Rebecca said. “But the money moved before he approved the reconciliation.”
“Exactly,” Miriam replied. “That may be why his name appears in so many of these documents. The agreement relied on his confirmation, even though the release was processed without it.”
The investigators requested the trust administrator’s archived correspondence. If the separate reserve had remained untouched, it might contain money that could be returned to the rightful claimants. If it had been transferred again, the records could reveal another stage of the arrangement.
At the same time, Miriam asked us to review Arthur’s remaining papers for references to Edmund North. We found no direct mention of him in the notebook, but one entry referred to a “private lender” who had been promised repayment from the reserve. Arthur had written that the lender’s claim might be legitimate, but the company could not satisfy it by pretending the claimant register was complete.
That sentence changed how I understood the conflict. Arthur had not necessarily believed every person receiving money was dishonest. He had objected to the method. A legitimate creditor could still be paid through an unauthorized transfer, and a valid debt could not erase the company’s obligations to claimants who had not received their money.
At the bottom of the page, Arthur had added a final note: Find the person who approved the exception. Voss says it was a board decision. Finch says no board vote occurred.
Harold Finch had already told us that Arthur insisted claims be verified before the release. Now Arthur’s own notes suggested that Voss had defended the exception by claiming the directors approved it, while Finch remembered no such vote.
Miriam arranged for the investigators to ask the surviving directors whether they had authorized the private agreement. If none of them had, the claim that the arrangement had been approved by the board would become another central contradiction.
Before the day ended, we received a message from Miriam. The investigators had found a set of meeting minutes from December 1987. The minutes recorded a discussion of the settlement reserve, but they contained no approval for the private repayment agreement.
Instead, the final paragraph stated that the directors had agreed to delay the release until the claimant schedule and supporting payment records were complete.
The minutes were signed by the meeting secretary.
The secretary was Leonard Voss.
Click here to continue reading: PART 28: The Board Minutes Contradict Voss’s Explanation and Bring Arthur’s Last Unfinished Investigation Into Focus
My Mother Wrote Six Ordinary Numbers, but the Man Behind the Counter Suddenly Forgot How to Breathe
Part 27 of 30