Miriam returned the next morning with a request from the investigators handling the financial records. They had located the bank that administered the nominee company’s account, but the original branch had closed decades earlier, and its records had been transferred several times. The institution could not immediately produce a complete statement. It had, however, found a surviving index card and two microfilm references associated with the account number Eleanor had kept in her tin box.
The index card contained a detail we had not seen before: the account had been opened with a deposit of one dollar, then converted into a holding account three days later. The card listed no ordinary customer signature. Instead, it referred to a corporate instruction filed under the nominee company’s registration number.
“Someone established the account before the Northfield transfer,” Rebecca said as she studied the copy. “They wanted it ready.”
“That is likely,” Miriam answered. “But we need the actual opening documents before we can say who arranged it.”
The second microfilm reference concerned an outgoing transfer made less than two weeks after the reserve money arrived. Its amount was substantially larger than the original deposit and nearly identical to the third distribution recorded in the Northfield ledger. The destination was not identified on the index card. It was described only as a numbered account maintained by another financial institution.
Eleanor sat quietly at the far end of the table. She had barely slept, she told us, and had spent most of the night trying to remember whether she had received any further letters from Voss. She remembered a telephone call around Christmas, during which he had said the arrangement had been completed and she would not be troubled again. She had understood that to mean the account had been closed.
“Did he tell you the money had been transferred?” I asked.
“No. He said the paperwork was finished. Those were his words.”
Miriam wrote down the distinction. “Did he ask you to confirm anything in writing?”
“No.”
“Did you ever receive a statement showing the balance?”
Eleanor shook her head. “I never saw a statement until this investigation began.”
That answer was consistent with her account, but the evidence still left an important question unanswered. If Eleanor had never controlled the money, someone else must have had authority over the account or access to its instructions. The nominee company had been a shell between Northfield Services and the ultimate destination, and the person behind it had taken care to leave as little as possible in the public record.
Miriam explained that the investigators were trying to reconstruct the transaction in stages. First, they needed to establish who created the nominee company. Then they needed to identify the person who supplied its instructions and the bank account that received the final transfer. Finally, they needed to compare those records with the private distribution schedule and the disputed second release.
“Every step matters,” she said. “If we skip one, the person responsible can claim that the money moved for an ordinary administrative reason.”
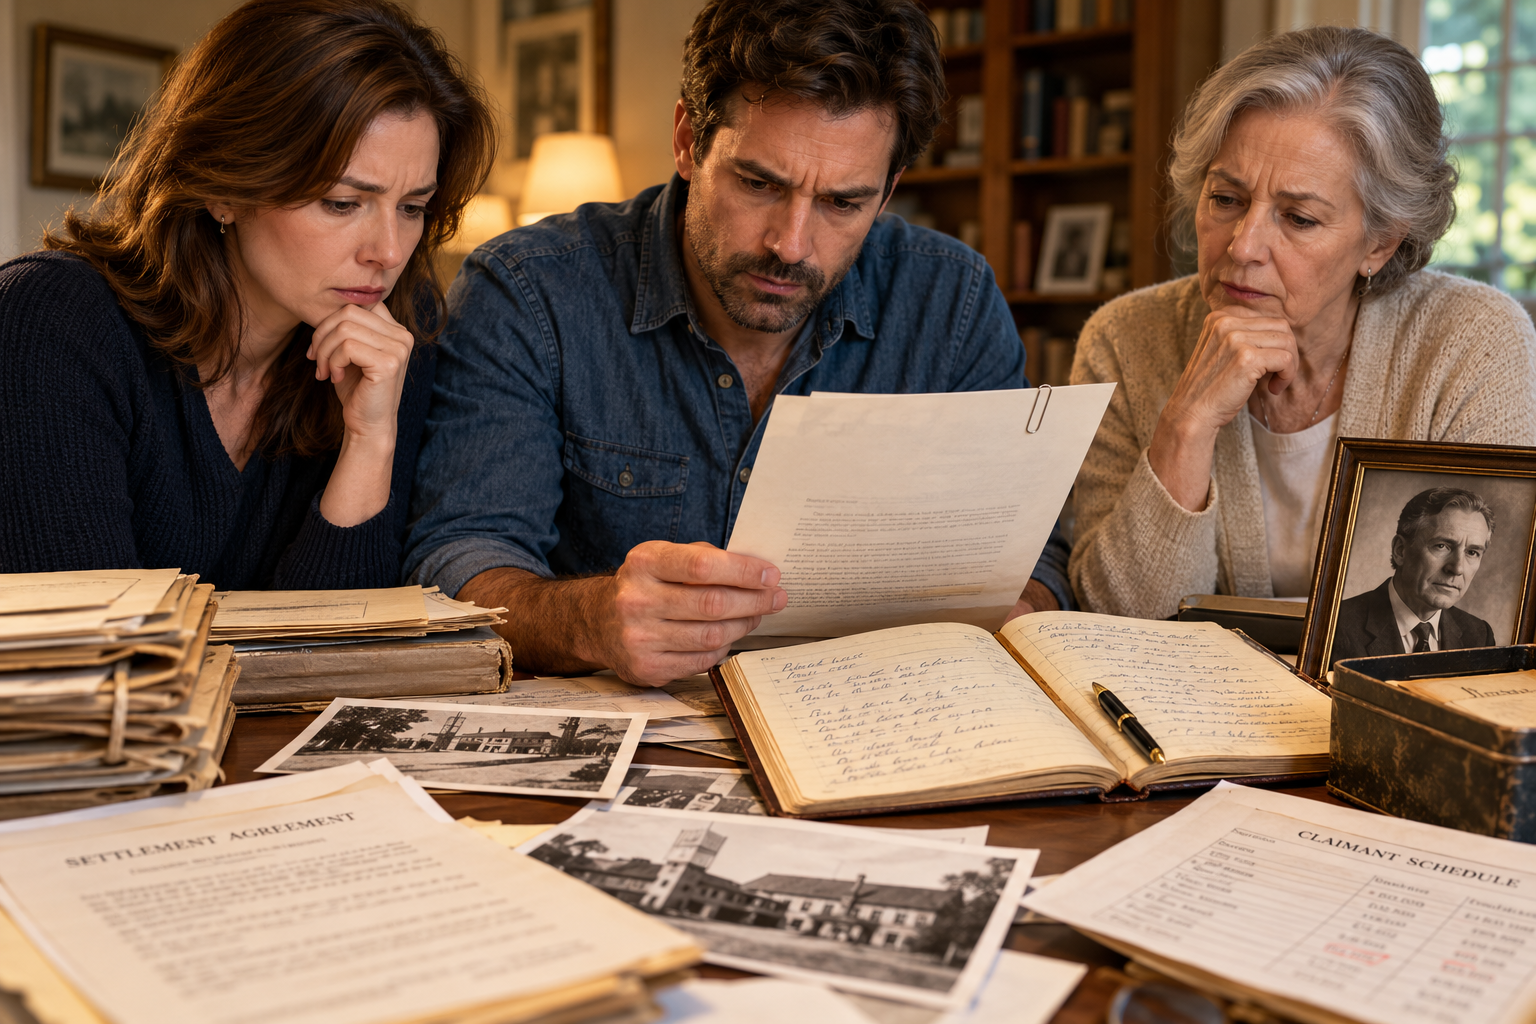
Rebecca had already opened a spreadsheet. She entered the date of the original transfer, the date of the outgoing payment, the amounts listed in the Northfield ledger, and the reference numbers from Martin Keene’s notes. A pattern began to emerge. The nominee account had not been used for ordinary business. It had received a single large payment and then sent most of that money elsewhere.
“The account was a corridor,” she said. “It was never the destination.”
I thought about Arthur’s warning that someone might use Eleanor’s name to make an unfinished settlement look complete. Perhaps the account had been created to disguise the recipient while making it appear that a member of the Brooks family had accepted the money. If the account appeared on a tax record, someone examining the transaction might assume that the family had received its share and that the settlement had been properly concluded.
But Arthur’s letter had been written before the transfer. He had known the account was being proposed and had expressly objected. If Voss had proceeded anyway, the account’s existence could not reasonably be treated as evidence of Arthur’s approval.
Later that afternoon, Miriam called with an update. The investigators had found a reference in the bank’s surviving transfer register. It identified the institution that received the outgoing payment, along with the date the funds were credited. The destination account had been held by a private investment company that was no longer active.
Its name was familiar.
Northfield Holdings.
Rebecca read it aloud, then checked the name against the old distribution agreement. Northfield Holdings had appeared in the agreement as an investor whose participation was essential to completing the settlement before the end of 1987. It was also the party whose threatened withdrawal had been remembered by Harold Finch, the former director who told us that Arthur had insisted on verifying the claims before the final release.
“So the money went back to the investor?” I asked.
“Possibly,” Miriam said. “But we cannot assume the investor and the beneficial owner were the same. A company can receive funds on behalf of another party. We need the ownership records and the company’s bank instructions.”
She sent us a copy of the register entry. The payment had been described as a repayment of an advance, not as a distribution to claimants. No corresponding repayment had appeared in the settlement agreement we had reviewed. The amount also included a small additional charge that had no explanation in the surviving documents.
Rebecca compared the date with the letter Voss had sent Robert Vale on December 10, 1987. In that letter, Voss had written that Arthur’s approval was already in the file and that no further confirmation was required. The following day, the reserve had been released. Less than two weeks later, the money had moved from Eleanor’s nominee account into Northfield Holdings.
The sequence was too orderly to ignore.
Miriam warned us that timing alone could not establish criminal intent. An investor might legitimately receive repayment of an advance, and an intermediary might be used for reasons that were not inherently improper. But there was no matching authorization, no completed claimant schedule, and no evidence that the disputed payment had been disclosed to the directors who approved the final accounting.
“What about the three claimants?” Rebecca asked. “Clara Whitcomb, the Miller family, and Bell Equipment. They were marked settled, but the payments don’t match.”
“That is still central,” Miriam said. “If money meant for those claimants was diverted to repay an investor, then the accounting may have concealed a direct loss. We need to prove that connection.”
She explained that the investigators had requested additional corporate records and were trying to identify the people who controlled Northfield Holdings at the time. The company’s registered director was not necessarily the person who made its decisions, and the surviving filings named an administrative agent who had represented several unrelated businesses.
I remembered the phrase in Arthur’s notebook: Third transfer not authorized. Account opened under false designation. Must locate original schedule before Voss closes file.
He had not written that the money was missing. He had written that the transfer was unauthorized and that the account had been opened under a false designation. He had understood that the name on the account was not the same as the person directing the transaction.
That evening, Eleanor handed Miriam a second page she had found folded inside the old bank notice. It was a handwritten telephone message, probably copied by someone in the legal office. The note recorded a call from Voss and included a brief instruction: “After credit clears, return funds to principal. Do not use claimant ledger.”
The word principal was underlined.
Miriam stared at the note for a long moment. “This is important,” she said. “It suggests the account was being used to move funds on behalf of someone else. It still doesn’t tell us who that principal was.”
Rebecca added the note to her spreadsheet. Beneath the existing entries, she typed a new line: Funds moved through Eleanor’s account; final destination Northfield Holdings; principal unidentified.
I watched the words appear on the screen. The money had crossed two accounts, carrying different descriptions at each stage. In the first ledger it had been part of a reserve distribution. In the second, it had appeared as a temporary holding. At its destination, it had become repayment of an advance.
Three descriptions, one transfer, and no authorization from the person whose signature was supposed to make the settlement final.
Before we went to bed, Miriam sent us a final message. The investigators had discovered that Northfield Holdings was not merely an investor in the settlement. It had been created by a partnership that included a person who had previously worked with Leonard Voss.
The partnership’s surviving records were incomplete, but one document contained a handwritten note beside the original capital contribution.
It said: “Beneficial interest held for L.V.”
The initials matched Voss’s name.
Click here to continue reading: PART 23: A Former Clerk’s Forgotten Copy Shows Why the Settlement Was Pushed Through Before Anyone Could Challenge It
My Mother Wrote Six Ordinary Numbers, but the Man Behind the Counter Suddenly Forgot How to Breathe
Part 22 of 30